
As South Korea’s financial services market becomes increasingly digital, financial institutions are competing on more than products and prices. Usability, personalization, and trust are emerging as critical factors in how customers evaluate financial platforms.
South Korea’s financial institutions are investing heavily in digital services and artificial intelligence, but consumer research suggests that adding technology does not automatically improve the customer experience. A Consumer Insight survey of 1,500 South Korean adults aged 20 to 69, conducted in September 2026, found that although 95% of respondents were aware of at least one AI feature in financial apps, only 50% had tried one. Just 12% said they turned to AI first when they needed help with a financial task. The findings point to a challenge for banks and fintech companies: technological availability does not necessarily translate into meaningful customer adoption.
As digital financial services become more established, the competitive question is shifting from which institutions offer the most features to which ones make financial tasks easier, more relevant, and more trustworthy. For South Korean financial companies, customer experience is becoming an important way to differentiate services in an increasingly crowded market.
South Korea’s financial services market includes established banking groups, internet-only banks, card issuers, and technology-led platforms. Consumers can manage payments, transfer money, review spending, and access financial products through a range of digital channels. In this environment, convenience is increasingly an expectation rather than a distinguishing feature.
The next challenge is usability. Financial institutions have continued to add functions to their applications, from asset management and product recommendations to customer support and investment information. However, a larger set of features can make an app harder to navigate if the services are not organized around customers’ needs.
This creates a difficult balance. Consumers may value having multiple financial services in one place, but they also expect to complete routine tasks without unnecessary steps or confusion. A platform that offers extensive functionality but makes common actions difficult can undermine the very convenience it is intended to provide.
For financial institutions, digital transformation therefore requires more than moving existing services onto mobile devices. It requires understanding how customers use those services and designing interactions around their priorities.
Design Is Becoming Part of Financial Differentiation
When financial products offer similar core functions, design can help companies establish a more recognizable identity. This extends beyond visual appearance to the way information is presented, how customers navigate a service, and how consistently a brand communicates across physical and digital channels.
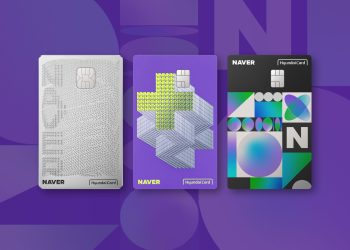
Hyundai Card has made design a visible part of its product strategy, including through its collaboration with NAVER and creative collective CEKAI on the NAVER Hyundai Card Edition3. But the company’s view of design extends beyond a single product.
While conversing with KoreaTechToday, a Hyundai Card spokesperson said, “We believe design can serve as an important means for Korean financial companies to communicate their unique identities in the global market.”
The spokesperson added that although NAVER Hyundai Card Edition3 was developed specifically for Korean customers, “the underlying approach of combining technology, visual culture, and product design is not limited to the Korean market.” The company believes this approach could resonate with customers in other markets.
The comments reflect a broader business question: how can financial institutions make products feel distinctive when their underlying functions are increasingly similar?
A recognizable design can help a product stand out, but its commercial value depends on more than appearance. The experience must also deliver practical benefits and remain consistent with the service customers receive. Design is most effective as a competitive tool when it reinforces usability and brand identity rather than functioning as decoration alone.
AI Can Personalize the Experience, but Relevance Matters
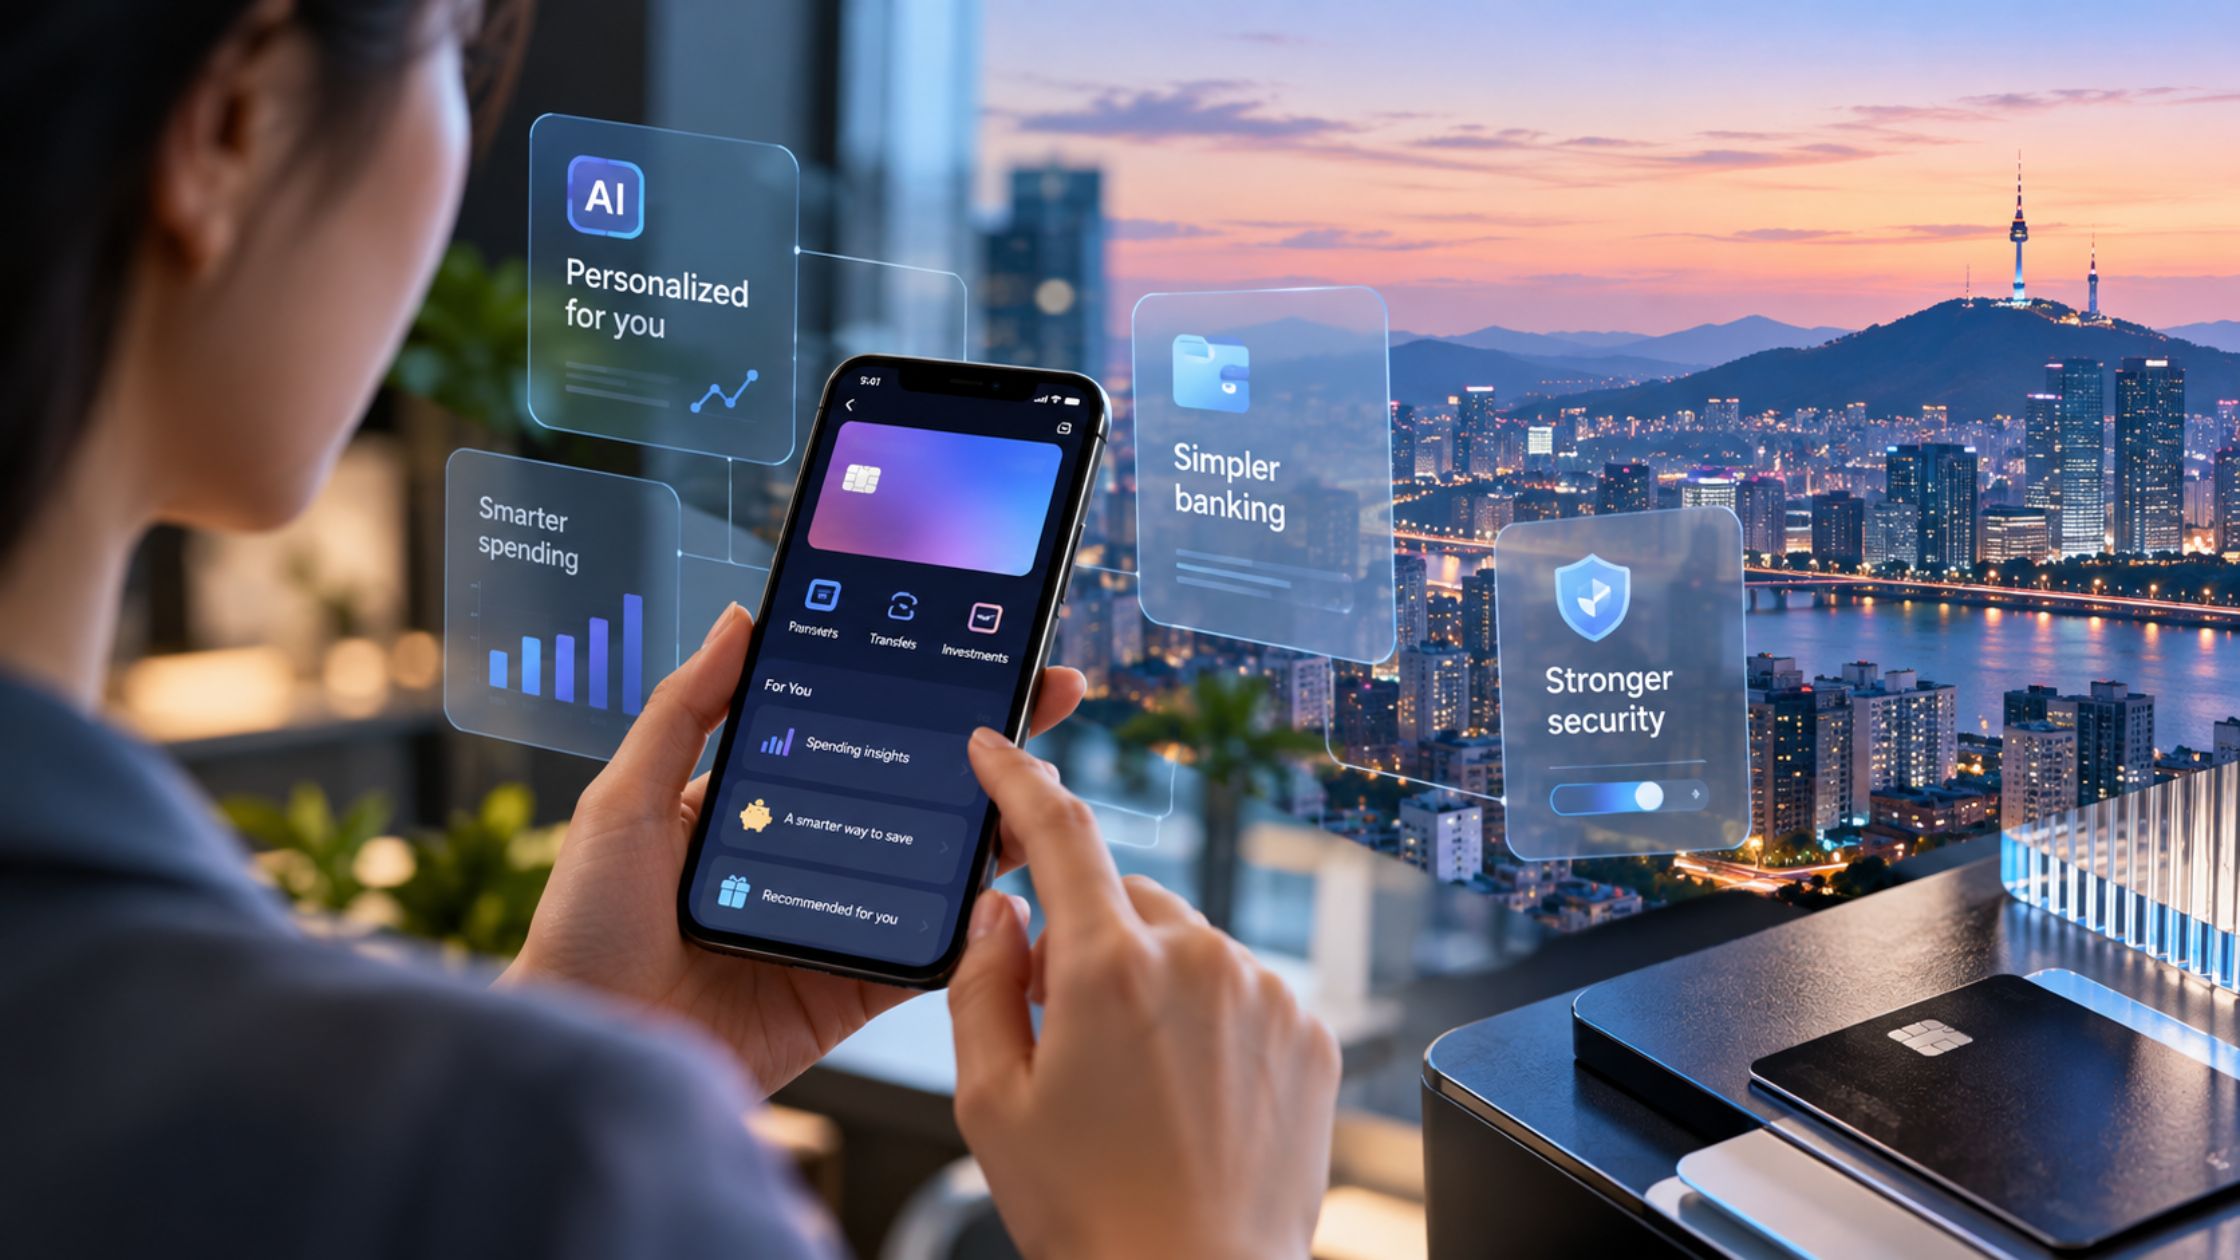
Artificial intelligence offers financial institutions another way to differentiate their services. By analyzing customer behavior, spending patterns, and preferences, AI systems can help companies tailor recommendations, identify relevant offers, and anticipate customer needs.
Hyundai Card’s proprietary UNIVERSE platform illustrates how data capabilities developed within financial services can support more targeted marketing. The company has also supplied the platform to Japan’s Sumitomo Mitsui Card Company, extending its AI capabilities beyond its domestic operations. These developments demonstrate how financial institutions can apply data science not only to internal processes but also to customer-facing business activities.
However, personalization does not automatically produce a better experience. Recommendations that fail to reflect customers’ circumstances can create frustration, while excessive marketing can make digital channels feel intrusive. The objective should be to make services more useful, not simply to increase the volume of automated interactions.
Recent consumer research highlights this gap. Consumer Insight found that among people who had tried AI features in financial apps, only 43% reported satisfaction. The most common complaints were answers that did not fit their individual circumstances and functions that offered guidance without completing the task.
For financial companies, this is an important distinction. AI that improves a company’s marketing efficiency does not necessarily improve the customer’s experience. The technology must solve real problems and deliver results that users can understand and act on.
Trust Will Determine the Value of Digital Innovation
The limitations of current AI experiences also highlight the importance of trust and customer control. In the Consumer Insight survey, 78% of respondents said they wanted to make the final decision on important financial transactions, even when AI was involved. Meanwhile, 77% said customers should be able to reach a human representative easily when AI could not resolve an issue.
These findings suggest that consumers do not necessarily reject automation. Rather, they expect technology to assist them without removing their ability to make consequential decisions. Financial services involve sensitive information and potentially significant financial consequences, making transparency, security, and access to human support essential parts of the experience.
For South Korean financial institutions, the challenge is to integrate design, data, and AI without making services more complicated or eroding customer confidence. The most successful platforms will not necessarily be those with the largest number of features or the most visible AI capabilities.
Instead, competitive advantage will depend on whether financial companies can translate technological investment into services that customers find genuinely useful. As digital finance matures, the quality of the customer experience will be measured less by what a platform can do in theory and more by how effectively it helps people manage their financial lives.