
As record venture funding flows into AI, semiconductors and other strategic technologies, Korean startups may face a new question: how can they stand out when investors are increasingly looking for similar technology themes?
South Korea’s venture market is entering a period of significant expansion. New venture investment reached KRW 8.87 trillion in the first half of 2026, up 54.3% from a year earlier and the highest first-half figure on record. New venture fund formation also rose 33% to KRW 8.44 trillion. Early-stage investment increased 56.4%, suggesting that the recovery is reaching younger companies as well.
Much of this momentum is connected to technology-intensive sectors. ICT services attracted KRW 1.86 trillion, while electrical, machinery and equipment received KRW 1.54 trillion and bio and healthcare received KRW 1.50 trillion. Large transactions involving AI chips, memory semiconductors and humanoid robotics also contributed to the increase.
The numbers point to a strong investment environment, but they also raise a more nuanced question. As AI and other strategic technologies attract increasing amounts of capital, does technological alignment make it harder for startups to demonstrate what is genuinely different about their businesses?
For European angel investor Urska Vracun, that is becoming an important consideration.
AI Is Part of a Broader Technology Investment Shift
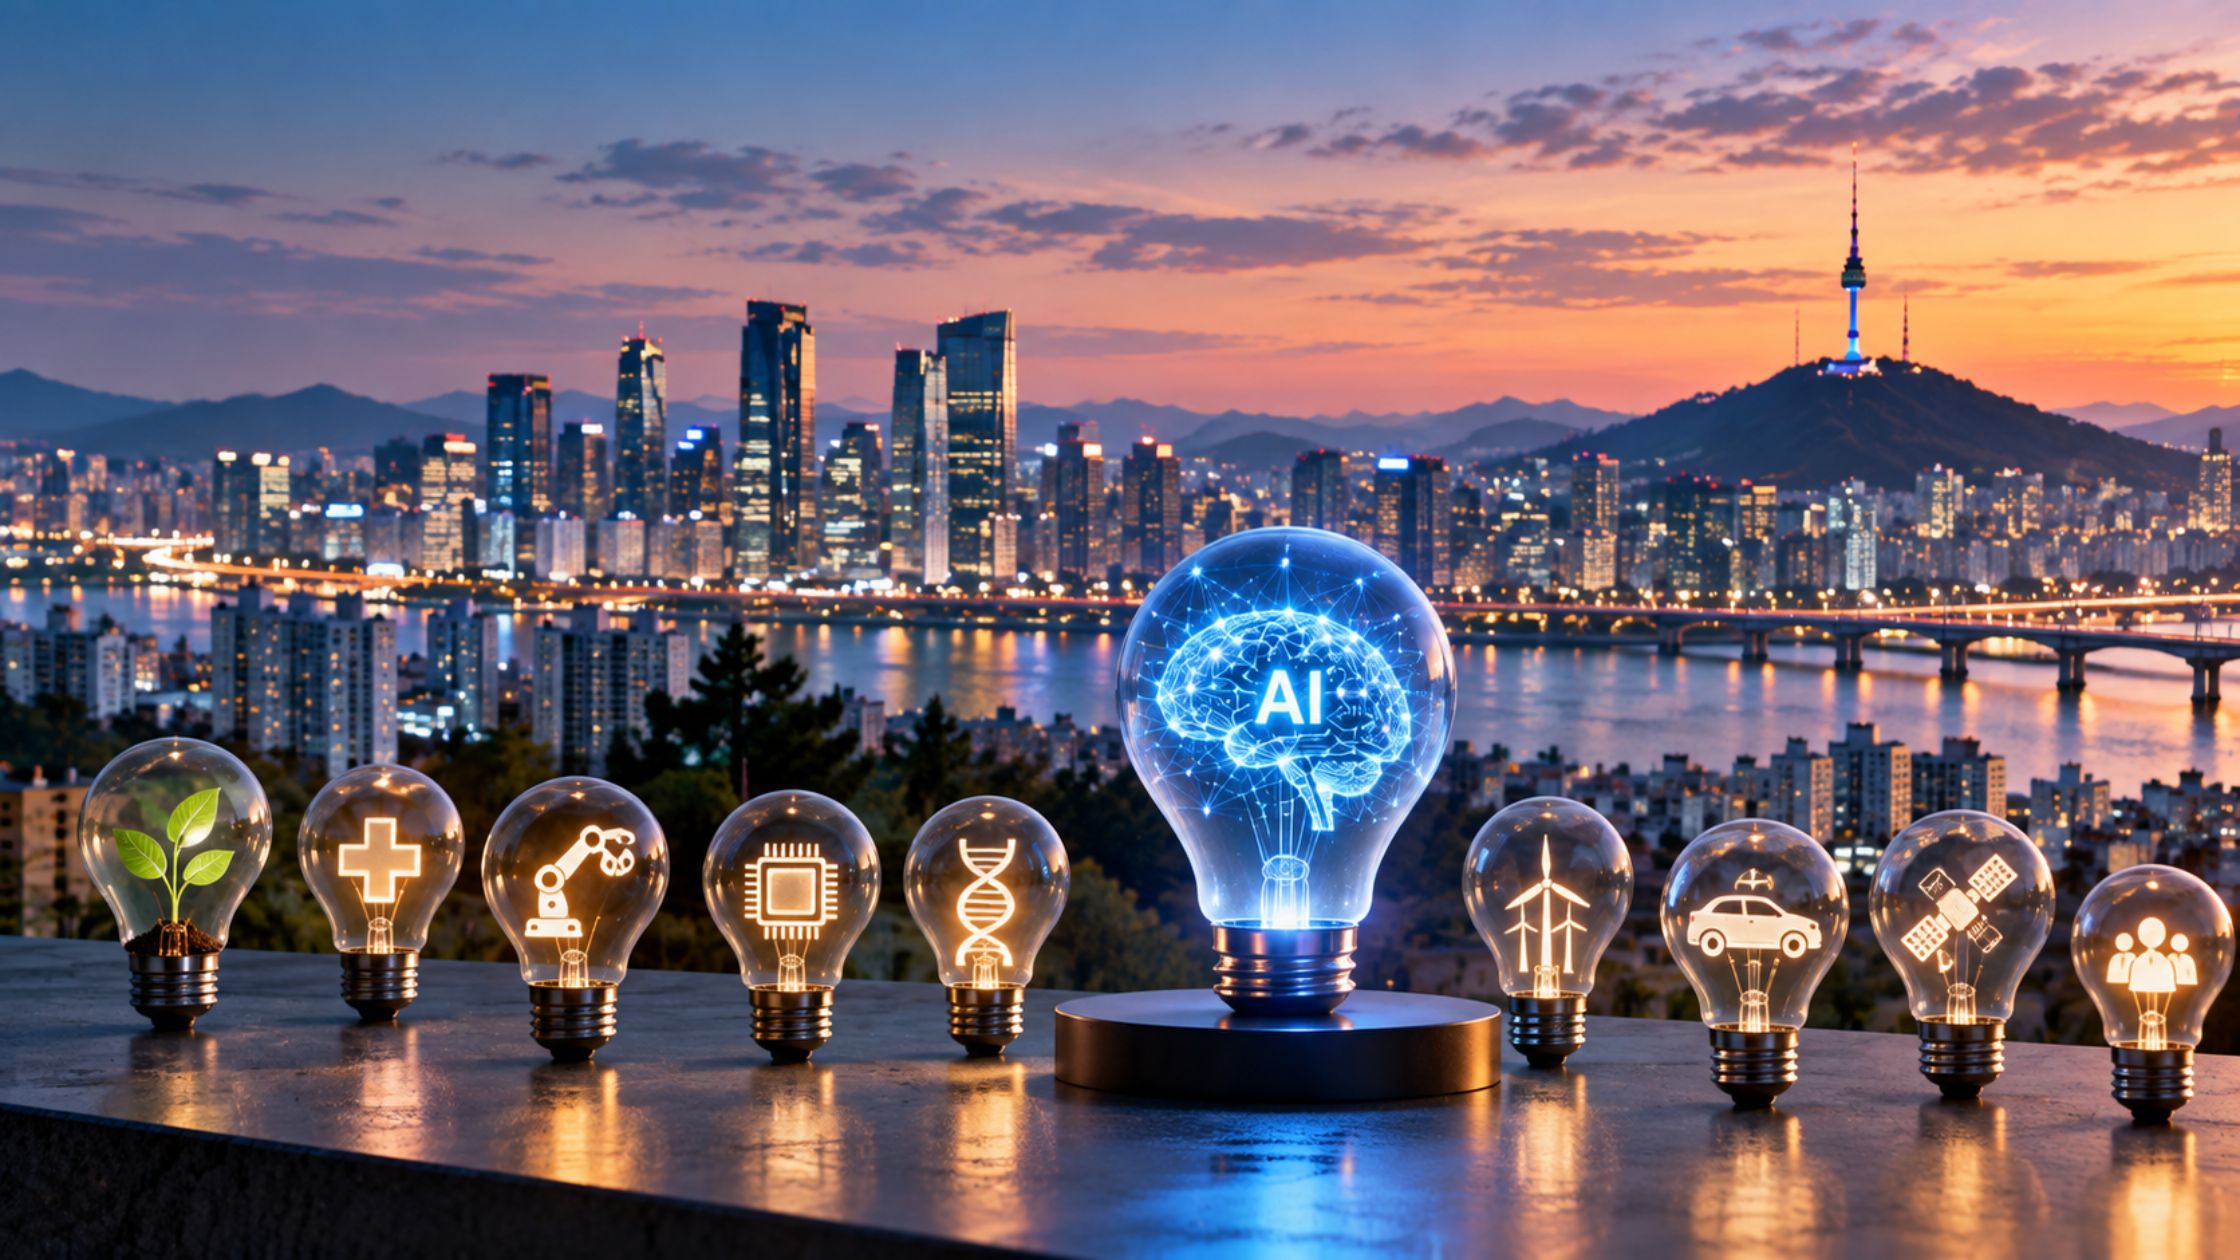
AI’s growing prominence in Korea’s venture market should not be viewed in isolation. In 2025, Korea’s 12 designated new-industry sectors attracted KRW 5.2 trillion, accounting for 76% of total venture investment. The group includes AI models and infrastructure, semiconductors, mobility, robotics, healthcare, life sciences, quantum and security, defense and aerospace, energy and other strategic industries.
This concentration also reflects deliberate industrial policy. Korea is directing capital and infrastructure toward technologies considered important to future competitiveness, while corporate investors are becoming more active in the startup ecosystem.
Corporate venture capital investment reached approximately KRW 2.9 trillion in 2025, representing 21.3% of total venture investment. The number of CVCs reached 114, and the government is also working with companies to establish open-innovation funds targeting areas including biotechnology, defense and beauty. The result is not simply an AI market. It is a broader technology ecosystem in which AI increasingly intersects with semiconductors, robotics, healthcare, manufacturing and other industries. That creates significant opportunities for founders. It also raises the standard for differentiation.
When AI Becomes an Investment Signal
The question is not whether startups should use AI. For many businesses, AI may be an important enabling technology or even the foundation of a new product category.
The question is whether using AI is itself becoming part of the investment positioning.
Urska Vracun, a European angel investor, said while conversing with KoreaTechToday:
“In my view, it is the second. Concentrating so much investment into such a narrow area is rarely beneficial for startups outside those sectors but also for the startups within the sectors attracting investment. The reason is that startups in AI or semiconductors, for instance, grow exponentially without real innovative inertia other than the investment potential. Naturally, even startup ideas which would work well without AI, will then include AI into their solution just to be eligible for the investment. This results in less differentiation which is already hard in today’s startup world.”
Her observation points to an incentive problem rather than an argument against AI investment.
When a particular technology becomes a strong investment signal, founders may have an incentive to emphasize that technology more prominently. In some cases, AI may fundamentally change the product. In others, it could become an additional layer over a solution whose underlying value comes from somewhere else. The distinction matters because increasingly accessible AI capabilities can reduce the technological barriers to launching similar products.
The Differentiation Question Is Moving Beyond the Technology Label
For investors, this potentially changes the question from “Does this startup use AI?” to “What does this startup have that another AI-enabled company cannot easily reproduce?” That could be proprietary data, a specialized workflow, deep industry knowledge, distribution, customer relationships, regulatory expertise or an established position within a particular industrial ecosystem.
Korea’s strength in manufacturing and advanced industries could be particularly relevant here. An AI startup integrated into semiconductor production, healthcare, robotics or industrial operations may have a different competitive position from a company offering a broadly similar AI capability without specialized access or domain knowledge.
This is where the growing role of corporate venture capital could become important. CVC investors can bring more than financial capital. Their strategic relationships, industrial infrastructure and customer networks can potentially help startups build differentiation through real-world deployment. Korea’s KRW 2.9 trillion CVC market gives founders another route to developing that kind of advantage.
More Capital Could Raise the Bar for Founders
Korea’s record investment numbers therefore do not necessarily signal a problem with its AI-focused venture market. They point to a market becoming more mature around technologies that investors and policymakers consider strategically important.
The challenge is what founders do with that opportunity. As capital becomes more available for AI, semiconductors, robotics and other priority technologies, simply belonging to one of those categories may become less distinctive. The startups that stand apart will need to demonstrate how technology translates into a defensible business.
That may be particularly important at the early stage, where Korea is seeing some of its fastest investment growth. Companies three years old or younger attracted KRW 1.83 trillion in the first half of 2026, up 56.4%. Nine early-stage AI and robotics companies alone accounted for KRW 315.3 billion across large rounds of KRW 10 billion or more. For these companies, the opportunity is substantial. But so is the need to explain why their particular approach matters.
Korea’s Next Venture Advantage May Be Application
Korea does not necessarily need less investment in AI. It may need a sharper definition of what makes an AI company investable. The country’s combination of semiconductor expertise, manufacturing capacity, industrial customers, research institutions and growing venture capital can create opportunities to build AI businesses around difficult real-world problems. The strategic advantage may therefore come from connecting AI to assets and capabilities that are harder to replicate than the technology itself.
That changes the differentiation test. An AI label can explain what technology a startup uses. It does not necessarily explain why the company will win. As Korea’s venture market enters a record growth phase, the next stage may therefore be less about attracting capital to AI and more about converting that capital into companies with distinctive technology, market access and execution. For founders, investors and corporate partners alike, the opportunity is not simply to participate in the AI boom, but to determine where AI creates a genuinely difficult-to-copy advantage.
Korea’s investment momentum is giving startups more room to build. The next question is whether that capital can help them build something that looks different once the AI label is removed.